New Jersey DMV Lien Check — Free VIN Lien Lookup
Check any New Jersey vehicle for an open loan or a lienholder on record before you pay for it. A lien is filed against the VIN, not against the piece of paper the seller hands you — so the only reliable way to find one is to search the number stamped on the car.
Run a Free New Jersey Lien Check
Enter any 17-character VIN — we'll surface any active or historical lien and the lienholder on record
Free · No sign-up · Instant result
How a New Jersey DMV Lien Check Works
Three steps turn scattered New Jersey Motor Vehicle Commission and lender records into a straight answer on whether the car is actually free to sell.
Enter the 17-character VIN
Find the VIN on the dashboard by the windscreen, on the driver-side door jamb, or on the New Jersey title itself. Check that all three match before you go further — a mismatch is a bigger problem than a lien.
We search the title and lending records
We cross-reference NMVTIS, New Jersey Motor Vehicle Commission title-brand feeds, and UCC-1 filings. Those are separate systems that record separate things, which is why a seller can be truthful about one and silent about another.
Read the lienholder and the status
The report names the lienholder, the filing date, and whether the interest is active or released. An open lien is not automatically a reason to walk away — it is a reason to change how you pay.
How New Jersey Records a Vehicle Lien
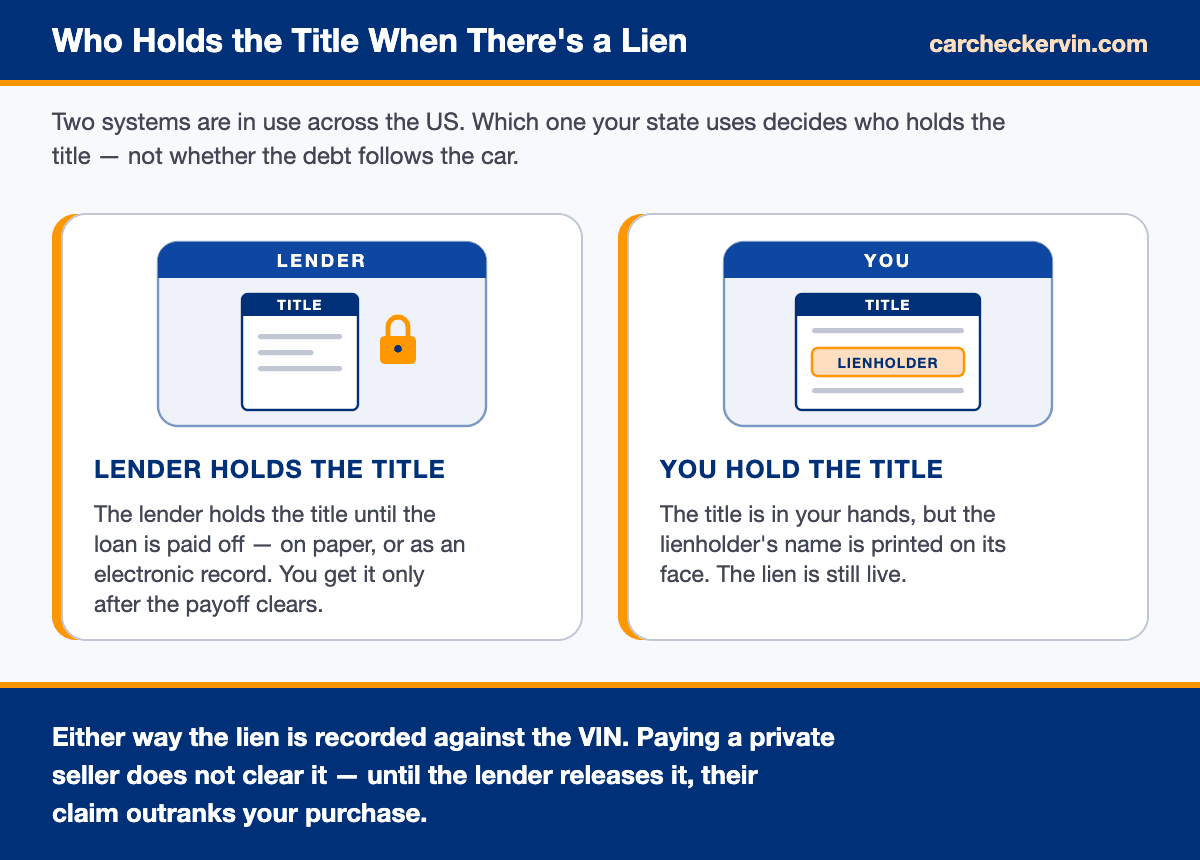
New Jersey does not let a borrower hold the paper at all. R.S. 39:10-11(B) provides that on a sale subject to a security interest the certificate of ownership, with the secured party's name and address recorded on it, "shall be delivered to the holder of the encumbrance or secured party or his assignee and a copy thereof shall be delivered to the buyer" — so a financed New Jersey seller has a copy, never the original, and the Motor Vehicle Commission puts it bluntly on its own lien page: "Customers shall not be given titles with liens; they can only be given to lienholders." That notation is also the whole of the register. Subsection (J) says the notation on the certificate of origin or certificate of ownership, together with presentation to the chief administrator, "shall be in lieu of all filing requirements imposed by chapter 9 of Title 12A of the New Jersey Statutes and shall constitute the perfection of a security interest in the motor vehicle". The one carve-out is dealer stock: subsection (E) leaves security interests in vehicles "which constitute inventory held for sale" to Article 9, so a car still on a dealer's floor plan is encumbered somewhere you cannot see from the title. A buyer has ten working days after purchase to submit the evidence of purchase to the chief administrator, and a $25 penalty for missing it.
The practical consequence is the same wherever the car is titled: the seller's document may read clean, or say nothing at all, while the state record still shows the encumbrance. Searching the VIN beats reading the title, because the seller controls the title and does not control the record.
New Jersey lien records at a glance
- Titling agency: New Jersey Motor Vehicle Commission
- How a lien attaches: Noted on the certificate of title
- Governing statute: N.J.S.A. 39:10-11
What an Open Lien Actually Does to Your Purchase
“There's still a bit owing on it” sounds like the seller's problem. Once money has changed hands it is yours. Three things follow from an unreleased lien, and they compound.
The title will not transfer
The New Jersey Motor Vehicle Commission will not issue you a clean certificate of title while another party's interest is on record. You can hold a signed bill of sale, the keys, and the car, and still not be the legal owner of it.
The lender can repossess
The security interest attaches to the vehicle, not to the borrower. If the seller stops paying, the lender's claim is against the car — sitting on your driveway — and your recourse is to sue the seller, who has already spent your money.
You cannot resell or borrow against it
An encumbered vehicle cannot be cleanly sold on, and no lender will accept it as collateral. The problem does not stay quiet until you try to leave — it surfaces at exactly the moment you need the car to be an asset.
Does This New Jersey Car Carry a Hidden Lien?
Don't rely on the paper title — it can look clean over an active loan. Run the VIN to see the lienholder and status, free, in seconds.
How a Lien Gets Released in New Jersey
New Jersey sets no deadline for a lender to release. R.S. 39:10-14(D) only says that when evidence of satisfaction or of termination of a security interest is presented, the chief administrator shall note it on the record. What the MVC does publish, and what a buyer should hold the seller to, is exactly which proofs it accepts. Best case, the seller has the original New Jersey title with the lien satisfaction signed and dated by an authorized representative of the lender, in which case no further proof of payment is needed. Otherwise the MVC wants a signed and dated lien satisfaction letter on official company letterhead naming every owner and giving the company's name, address and telephone number together with the VIN, year and make matching the title; or a motor vehicle dealer wire transfer statement with a transaction number; or a retail installment agreement with a matching VIN, stamped with the bank's name and dated. A lien satisfaction letter from an individual lienholder who is not a financial institution has to be notarised. Getting a clean title reissued costs $60 at a motor vehicle agency or by post to the Database Corrections Unit, PO Box 141, Trenton, and the MVC reserves the right to ask for further proof of payment.
Whatever the mechanism, the thing to insist on is evidence rather than assurance. A release that has been filedis a record you can verify by VIN. A release the seller says is “coming in the post” is not a fact about the car — it is a fact about the seller.
Buying safely when the loan is still open
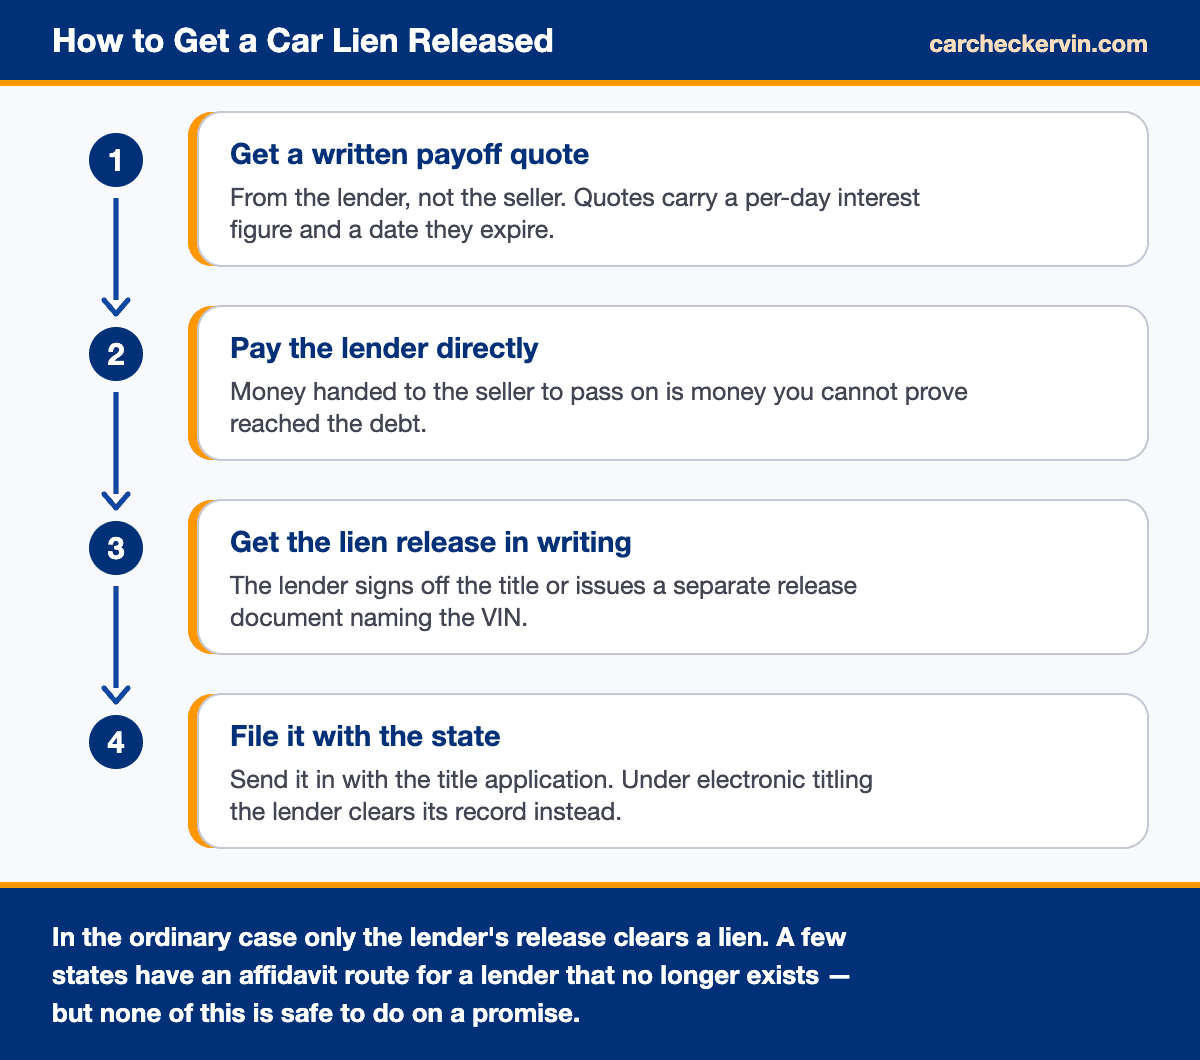
Most private sales of financed cars are honest — the seller owes less than you are paying and simply needs your money to clear the loan. That is a solvable problem, and the solution is to never let the payoff pass through the seller's hands.
- 1Ask the seller for a written payoff quote from the lender, showing the exact amount and a good-through date. Verbal figures drift.
- 2Pay the lender directly for the payoff amount, and pay the seller only the balance. Two payments, not one.
- 3Complete the transaction at the lender's branch where possible, so the release is generated while you are standing there.
- 4Get the lien release document, then re-run the VIN before you register the car to confirm the record actually cleared.
- 5Only then file the transfer with the New Jersey Motor Vehicle Commission and put the car in your name.
Red Flags of a Hidden Lien in New Jersey
- Seller cannot produce a physical title, or produces only a photocopy
- Title names a lienholder with no recorded satisfaction or release
- Cash only; refuses cashier's cheques, escrow, or any traceable payment
- Only a duplicate title or a certified copy is available
- Asking price well below market with no verifiable explanation
- Pressure to complete quickly and skip the paperwork
- Seller's name does not match the name on the title
- Seller wants to meet somewhere other than their home address
How to Read the Lienholder Line on a New Jersey Title
Buyers are handed a title, glance at it, and hand over money. Three fields on that document decide whether you are about to own the car, and they are worth reading slowly.
The lienholder name and date
If a bank, credit union or finance company is printed there, a loan was recorded against this VIN. That alone does not mean money is still owed — it means a security interest was filed and something must show it was discharged. An empty lienholder field on an older NJ title means no lien was recorded when the title was printed, which is not the same as no lien existing today.
The release or satisfaction block
A discharged lien usually leaves a mark: a signed and dated release section, a stamp, or a reissued title printed after the payoff with the lienholder field blank. A title that still names a lender and carries no release is an open lien until the state record says otherwise.
Whether it is a duplicate
Duplicates are usually innocent — people lose titles. But a duplicate is also how a seller produces a clean-looking document while the original sits with a lender, and how the same car gets sold twice. If the title is marked duplicate, treat the paper as unverified and go to the record.
None of this is a substitute for the record, and that is the honest summary of the whole section: the title is a printout of what the state knew on the day it was issued. The VIN search is what the state knows now. The same document carries two other things worth reading before you pay — any damage brand New Jersey has printed on it and the mileage certified at the last transfer. A lien can be paid off; neither of those can.
Four Places a Lien Hides Behind a Clean Title
The awkward cases are not the ones where the title names a lender. They are the ones where it does not, and money is still owed on the car.
The lien was recorded in another state
Titles move. A car financed elsewhere and retitled in New Jersey can carry a security interest that the newer NJrecord does not restate, particularly if the retitling happened quickly or across a state line where the paperwork is thinner. This is why a VIN check that reads national NMVTIS data matters more than a single state's screen: it sees the title history, not just the current title. The same gap is what lets a branded New Jersey title come back unbranded.
The debt is against a business, not the vehicle
Fleet, work and ex-lease vehicles are often financed on a blanket UCC-1 filing covering a company's equipment. Nothing appears on the car's title, because the lender's interest is in the business's assets rather than in that specific VIN. If you are buying from a contractor, a small fleet, or a company winding down, this is the failure mode to look for.
A repair shop or storage yard has a lien
Mechanic's and storage liens arise from unpaid work or unpaid fees, not from a loan, and they attach after the title was printed. They can be enforced against the car regardless of who owns it. A car that has sat at a shop for months and is now being sold in a hurry deserves a direct question about what is owed on it.
The payoff happened but nobody filed the release
The most common case, and the least sinister. The loan is genuinely paid; the lender was slow, or the release went to an old address. It still blocks registering the car in New Jersey, because the New Jersey Motor Vehicle Commission works from what is filed, not from what is true. Sorting it out before the sale takes a phone call. Sorting it out after takes weeks, with your money already gone.
You Already Bought the Car and There Is a Lien
This page mostly exists to stop that happening, but people arrive here after the fact, so: the situation is bad, not always hopeless, and moving quickly matters more than anything else you do.
- 1Find out what is actually owed. Call the lienholder named on the title with the VIN. They will not discuss another person's account, but they will normally confirm whether the lien is still open, which is the only fact you need first.
- 2Contact the seller in writing. Text and email are evidence; a phone call is not. Ask for the payoff to be completed by a specific date. Many sellers in this position intended to pay the loan off and did not, and a written deadline is often enough.
- 3Work out whether paying it off yourself is cheaper than the alternative. If the remaining balance is small against what you paid, clearing it and pursuing the seller for that amount can beat losing the car to repossession while you argue.
- 4Report a dealer to the state. New Jersey regulates licensed dealers, and selling a vehicle with an undisclosed lien is squarely the kind of complaint the regulator exists for. This route does not exist for private sales.
- 5Get a lawyer involved before the lender does. Repossession does not require the lender to care that you were not the borrower — their interest is in the car. A small-claims or fraud action against the seller is a separate matter from keeping the vehicle, and the two run on different clocks.
General information, not legal advice. Lien enforcement and buyer remedies vary by state and by the terms of the loan.
Checking the Official New Jersey Record
A free VIN check tells you whether there is something to worry about. The state's own record is what you use to confirm it before a large payment — the two are complements, not substitutes.
One thing to know before you click. The federal Driver's Privacy Protection Act limits who may be given a motor vehicle record, and being a prospective buyer is not on its list of permitted uses. Expect to need the seller's written consent — or, simpler, ask the seller to request the record themselves and send it to you.
Application for Title/Lien Search (Form DO-22)
Fee: $15.00 per search
Open the official NJ record searchWhat a Lien Check Does Not Tell You
A lien is a fact about the car's finances. It says nothing about the car's history, and the two failure modes are independent — a vehicle with no lien at all can still have been written off, rolled back, or reported stolen. These are separate records and separate searches.
More New Jersey Vehicle Guides
Everything else worth knowing before you put a New Jersey car in your name.
DMV Lien Check in Other States
View the full DMV lien check hubNew Jersey DMV Lien Check — Frequently Asked Questions
How do I run a New Jersey DMV lien check?+
Enter the vehicle's 17-character VIN in the search box on this page. The lien is recorded against the VIN rather than against whatever paperwork the seller is holding, so a VIN search reaches it even when the document in front of you looks clean. We cross-reference NMVTIS title records, New Jersey Motor Vehicle Commission title-brand feeds, and UCC-1 filings to show whether the car carries an active lien and who the lienholder is.
What happens if I buy a New Jersey car with an active lien?+
You do not get clear ownership. The lienholder keeps a security interest in the vehicle until the debt is paid, and the New Jersey Motor Vehicle Commission will not transfer a clean title into your name while that interest is on record. If the seller stops paying after you have handed over the money, the lender can repossess the car from you — you would be left suing the seller for the purchase price rather than keeping the vehicle.
Can I check a New Jersey lien on the official state record?+
New Jersey publishes one — the Application for Title/Lien Search (Form DO-22), at $15.00 per search — though whether you can personally pull it is a separate question from whether it exists. The federal Driver's Privacy Protection Act limits who may be given a motor vehicle record, and wanting to buy the car is not one of the permitted uses. Some states answer a plain lien or title status query for anyone holding the VIN; most release the full record to the registered owner, or to you with the owner's written consent. The move that works is to ask the seller to pull it, or to have them sign the consent line on the request — a seller who refuses has told you something useful. A free VIN check needs nobody's permission, so run that first: it tells you whether there is anything worth chasing before you pay a fee.
Is a lien the same as a salvage or rebuilt title brand?+
No, and confusing them is a common and expensive mistake. A lien is a debt secured against the car and it can be cleared by paying the loan off. A title brand is a permanent statement about the car's history — that it was written off, flooded, or had its mileage rolled back — and no payment removes it. A car can carry both, one, or neither, and you need to check for them separately.
Can a New Jersey seller hide a lien from me?+
They can hide the paperwork, but not the record. A private seller can hand you a photocopied title, a duplicate, or nothing at all, and none of that changes what the state has filed against the VIN. This is the whole reason to search by VIN rather than to read the document you are shown: the document is produced by the person with an incentive, the record is not.
New Jersey sources
The New Jersey-specific statements above come from these official pages. Fees, forms and deadlines do change — check the source before relying on a figure for a transaction.
Vérifications VIN connexes
Plus d'outils pour vérifier l'historique de tout véhicule
Run Your Free New Jersey Lien Check Now
Two minutes now, against a debt that would otherwise follow the car into your name. Enter the VIN and see every recorded lien and lienholder on file.