Maryland Salvage Title Check by VIN — Is the Title Clean?
A salvage brand is recorded against the VIN, not against the document the seller hands you. Run the number and you see every brand the car has collected in Maryland and in every other state it has passed through — including the ones a re-issued title no longer prints.
Run a Free Maryland Salvage Title Check
Enter any 17-character VIN — cars, trucks, SUVs, motorcycles
Free · No sign-up · Instant result
How a Maryland Salvage Title Check Works
Three steps turn scattered insurer, auction and Maryland Motor Vehicle Administration records into a straight answer on whether this car has ever been written off.
Enter the 17-character VIN
Read it off the plate at the base of the windscreen, the driver-side door jamb, and the Maryland title, and check all three agree before you go any further. A VIN that does not match across the car is a bigger problem than any brand.
We search the national brand record
The lookup queries NMVTIS, which the Maryland Motor Vehicle Administration and all other state titling agencies report into, plus insurance total-loss feeds and salvage-auction listings. Those are separate systems, and a car can appear in one before it appears in the others.
Read every brand, in every state
The result shows each brand ever applied to the VIN and the state that applied it — not just what Maryland currently prints. A brand from a previous state is the single clearest sign the paper title in front of you has been washed.
What Counts as a Total Loss in Maryland
A total loss is an accounting decision, not a verdict on whether the car can be fixed. Almost any vehicle can be repaired given enough money. The insurer stops when repairing costs more than the car is worth, writes the owner a cheque for its value, takes the wreck, and notifies the state — and it is that notification, not the crash, that produces the brand.
Maryland draws the line at 75% of the vehicle's pre-loss value. That is the estimated cost of repair set against what the car was worth the morning of the crash. Who that test actually binds is a separate question, and it is worth knowing before you read the figure: in some states the insurer's own total-loss declaration is what brands the car and the percentage never enters into it, while in others the percentage governs only damage that no insurer is paying for.
Maryland brands at 75 percent of pre-damage fair market value, but the definition has two other independent limbs that catch far more cars. Transportation § 11-152(a) makes a vehicle salvage if it "[h]as been damaged by collision, fire, flood, accident, trespass, or other occurrence to the extent that the cost to repair the vehicle for legal operation on a highway exceeds 75% of the fair market value of the vehicle prior to sustaining the damage", or if it "[h]as been acquired by an insurance company as a result of a claim settlement", or if it has been acquired by an automotive dismantler and recycler either as an abandoned vehicle or "[f]or rebuilding or for use as parts only". The percentage is only one of three ways in, which is why a Maryland salvage document does not necessarily imply a repair estimate near three quarters of the car's worth — the insurer limb needs no arithmetic at all, and the dismantler limb needs no crash.
Two refinements to the arithmetic are written into the code and both favour the car. Under § 13-506(c)(4) the person doing the sum "may not use the cost of: (i) Towing, storage, or vehicle rental; or (ii) Repairing cosmetic damage" — so dents, scuffs and paint are stripped out of the estimate that decides the brand, along with the storage bill that is often the largest single line on a total-loss file. The practical effect is that a car can be genuinely uneconomic to fix and still sit under the statutory 75%, because the number the statute cares about is narrower than the number the adjuster is actually looking at. And § 13-506(c)(5) adds that the calculation "may not affect the right of an insurer or a vehicle owner to make an economic or safety related decision to not repair the vehicle", meaning a car can be walked away from without ever touching the threshold.
Maryland salvage rules at a glance
- Titling agency: Maryland Motor Vehicle Administration
- Total-loss test: Fixed percentage of pre-loss value
- Salvage threshold: 75% of pre-loss value
- Governing statute: Md. Code, Transp. §§ 11-152 ("Salvage" defined); 13-117 (corrected certificate of title); 13-506 (salvage certificates); 13-506.1 (owner retention); 13-507 (title after salvage); 13-810(a)(9) (excise tax exemption); 15-501 (automotive dismantler and recycler defined); 23-106 (inspection certificate on transfer); 25-201 (abandoned vehicle defined)
- Salvage brand wording: Salvage
- Rebuilt brand wording: rebuilt salvage
- Out-of-state brand carried forward: Yes
Check this MD VIN for a brand:
The denominator matters as much as the numerator. It is fair market value "prior to sustaining the damage", so the same physical wreck crosses the line on a nine-year-old economy car and stays well under it on a two-year-old truck. Nothing in the statute fixes how that value is established beyond the § 13-506(c)(4) exclusions, and § 13-506(c)(6) simply directs the Administration, "in consultation with the Department of State Police and other interested parties", to adopt regulations to implement the subsection. Two adjusters can therefore reach different answers on the same car without either being wrong on the face of the statute.
Section 11-152(b) then says something that looks, on a first reading, like a wide-open exit: "a vehicle has not been acquired by an insurance company if an owner retains possession of the vehicle upon settlement of a claim concerning the vehicle by the insurance company." Read alone, that appears to mean an owner-retained total loss escapes the insurer limb entirely and therefore escapes branding unless the repair estimate independently cleared 75%. That reading is wrong, and it is worth stating plainly because it circulates widely. It survives only if you stop reading at Title 11.
Section 13-506(a-1) repeats the same carve-out and then attaches a condition the definition section leaves out — the owner must retain possession "in accordance with § 13–506.1 of this subtitle". Section 13-506(b)(3)(i) separately requires the Administration to issue a salvage certificate to any other person who "[a]cquires or retains ownership of a vehicle that is salvage". Those two words, "or retains", are the whole point: the carve-out is not an exemption from the branding scheme, it is a routing instruction that sends the owner-retained car down a different corridor of the same building. Section 13-506(e) closes it off, requiring MVA to keep records showing the vehicle "[w]as transferred as salvage" and "[m]ay not be titled or registered for operation in this State except in accordance with §§ 13–506.1 and 13–507 of this subtitle".
Section 13-506.1 is where the owner-retained car actually goes, and it puts the reporting duty on the insurer rather than the owner. The company "shall promptly notify the Administration" if it "makes a claim settlement on a vehicle that is salvage" and "[t]he owner retains possession of the vehicle". The notice must be accompanied by the title itself plus a corrected-title fee under § 13-117, must name the owner and describe the vehicle, and must state which of the § 13-506(c)(2)(ii) notations applies. On receipt, MVA must "[r]ecord that the vehicle has been declared salvage" — a permanent entry made without the owner doing anything and without the car ever being inspected.
What happens next depends on which notation the insurer picked. For a repairable over-threshold car or a flood car (notations 1 and 4), MVA sends a notice "that the vehicle registration will be suspended unless the owner submits proof satisfactory to the Administration that the vehicle has been inspected for safety, in compliance with Title 23 of this article, within 90 days of the date of the notice" — that notice is MVA form VR-310. Once that safety inspection is done, § 13-506.1(d) requires MVA, "[i]n accordance with § 13-507 of this subtitle", to "issue to the owner a new certificate of title for the vehicle", which is what pulls the § 13-507(b) brands onto it. For a parts-only car (notation 2), MVA issues a salvage certificate and sends notice "that the vehicle registration has been suspended and directing that the vehicle's registration plates be returned immediately".
MVA's own form settles it in dollars. VR-028 states that "Maryland Vehicle Law §13-506.1 requires the insurance company to promptly notify the Motor Vehicle Administration of vehicles that have been settled as a salvage and are being retained by the owner. The fee will be $60.00", and that "[i]f the applicant checks boxes 1 or 6 in Section C, a corrected Certificate of Title bearing the appropriate brand will be issued. The fee will be $60.00." Box 1 is damage over 75% and repairable; box 6 is flood damage. Box 3 — not rebuildable, parts only — produces "a Salvage Certificate bearing the appropriate brand" for $40.00. The form then adds the line that closes the argument for good: "Section C boxes 2, 4, 5 and 8 are not applicable for owner retention." Box 2 is "[d]amage is 75% or less of fair market value", so an owner-retention filing cannot be used to declare a sub-threshold car. Every route the form leaves open to a retaining owner ends in a brand.
The carve-out does still do work, but a narrow kind. Section 13-506.1(a)(1) is triggered by a settlement "on a vehicle that is salvage" — so if the damage is 75% or less of pre-damage value and the owner keeps the car, there is no salvage vehicle for the insurer to report, and § 11-152(b) prevents the settlement itself from making one. That is the real gap: a below-threshold claim paid out on a car the owner keeps leaves no Maryland brand. It is a gap about small and moderate damage, not about total losses, and it says nothing about how the car actually drives. For anything at or over the line, the owner-retained car is recorded, its registration is put at risk, and it comes back on a branded title.
The rule sits in Md. Code, Transp. §§ 11-152 ("Salvage" defined); 13-117 (corrected certificate of title); 13-506 (salvage certificates); 13-506.1 (owner retention); 13-507 (title after salvage); 13-810(a)(9) (excise tax exemption); 15-501 (automotive dismantler and recycler defined); 23-106 (inspection certificate on transfer); 25-201 (abandoned vehicle defined).
What follows from that: the brand records an economicevent. A ten-year-old car with a book value of a few thousand dollars can be totalled by a shunt that would barely register on a new one, and it is the cheap car that gets branded. Read a salvage brand as “the repair bill was large relative to this car”, then go and find out what the damage actually was.
The Three Total-Loss Regimes, and Why They Matter to You
There is no national rule for when a damaged car becomes a salvage car. Each state picks one of three tests, and the choice decides whether an identical wreck leaves the body shop with a brand or without one.
Percentage of value
The most common test. The state fixes a percentage of the car's pre-loss actual cash value, and an insurer whose repair estimate reaches it must report a salvage. Thresholds run from about half the value to the whole of it, so the same $6,000 estimate on a $10,000 car is a mandatory brand in one state and a routine repair in another.
Total loss formula (TLF)
Repair cost plus salvage value, measured against actual cash value. TLF is sensitive to the parts market — a truck with hungry demand for its doors and tailgate totals on less damage than a car whose panels nobody wants.
Insurer discretion
No statutory trigger. The carrier decides when repair stops making commercial sense, on internal thresholds that are neither published nor binding. Two insurers can look at the same photographs and reach different answers, and neither is breaking a rule.
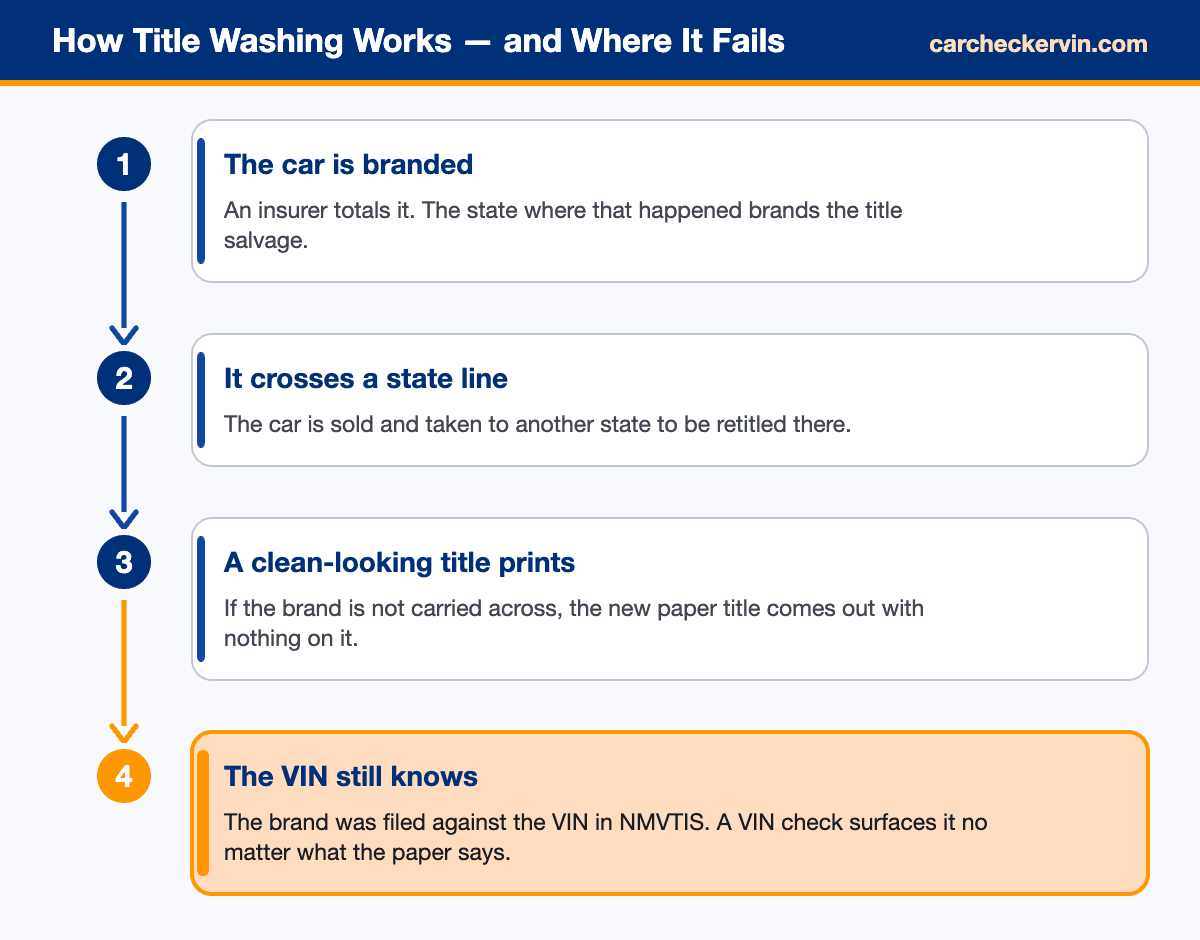
The consequence cuts both ways, and it is the reason to check the record rather than the paperwork. A cheap salvage car from a low-threshold state is not necessarily badly wrecked — it may have been branded on arithmetic another state would never have applied. An unbranded car from a high-threshold or discretionary state is not necessarily undamaged. It also makes moving damaged cars between states a business: a rebuilder who buys a wreck, repairs it and re-titles it where the brand does not carry across ends up holding a clean-looking certificate on a written-off car, without forging anything. That is title washing, and it is the same route by which a mileage brand gets left behind — which is why the two are worth checking together.
NMVTIS is the answer to that gap. Every state titling agency, insurer, salvage yard and recycler reports into it, and it is keyed to the VIN rather than to any document. A second state can print a fresh certificate; it cannot delete the record of the first one. The title is produced by the person selling you the car. The record is not.
Maryland Title Brand Vocabulary
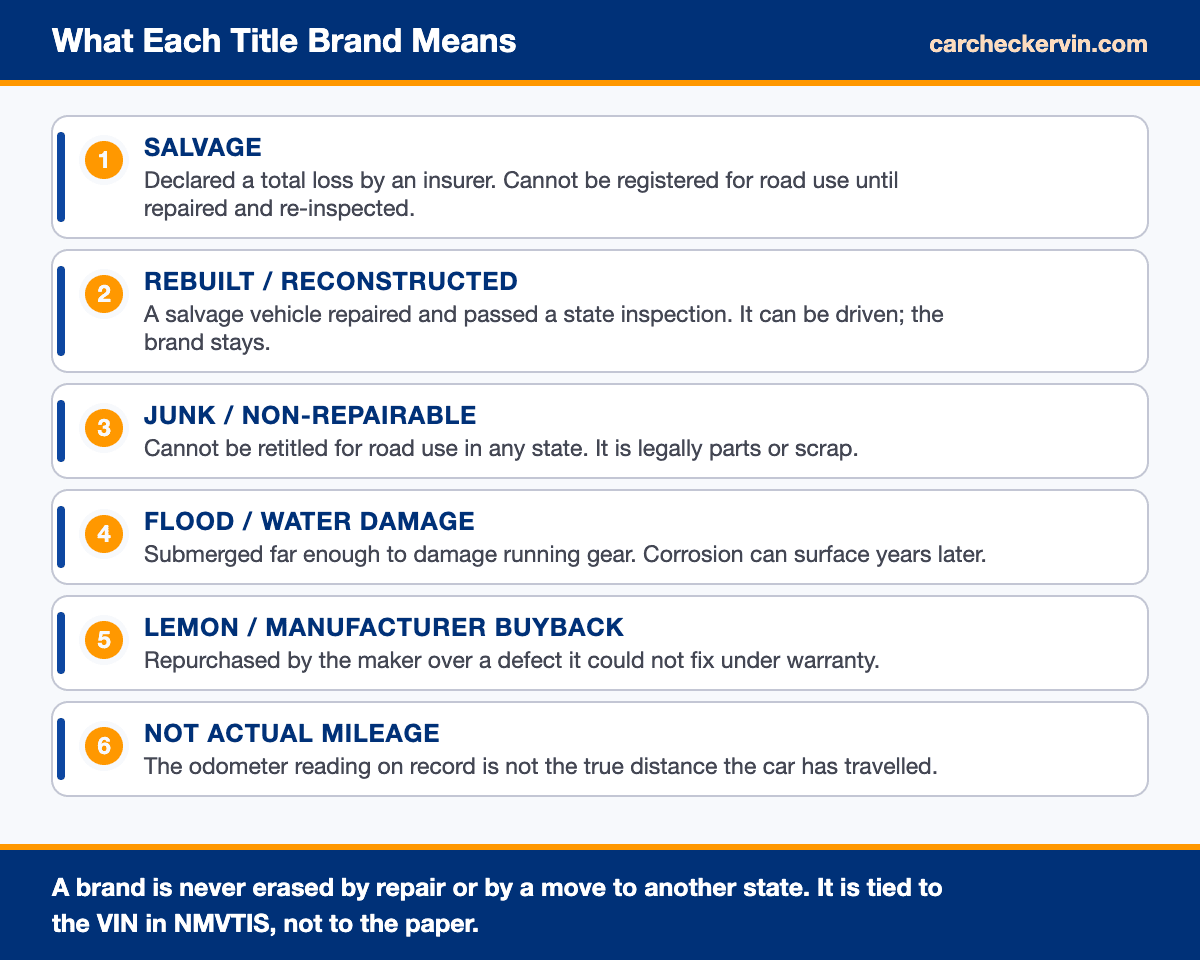
States do not use the same words for the same thing, and the words are not decoration — they decide what you are allowed to do with the car. These are the brands the Maryland Motor Vehicle Administration applies. Each one surfaces in a VIN check no matter which state later issues the title.
Issued when an insurer declares a vehicle a total loss — usually when repair costs reach roughly 65–100% of its value, depending on the state. A salvage vehicle cannot legally be driven until it is repaired, inspected, and re-titled.
A salvage vehicle that has been repaired and passed inspection to return to the road. The vehicle's total-loss history stays on its record permanently and affects value and insurability.
Marks a vehicle damaged by water submersion. Flood cars frequently develop hidden electrical faults, corrosion, and mold months or years later — often after cosmetic cleanup hides the evidence.
Means the vehicle is too damaged to ever be legally returned to the road. It can be sold only for parts or scrap — never re-titled for driving.
Maryland does something most states do not: it brands the salvage certificate by category, and the category decides whether a title can ever exist. Section 13-506(c)(3) requires the certificate to carry "a conspicuous notation by the Administration that describes which of the statements under paragraph (2)(ii) of this subsection applies to the vehicle", and the insurer picks from a fixed list of five — over 75% and repairable; not rebuildable, parts only and not to be retitled; stolen; flood damage; or acquired in a claim settlement at 75% or less. The insurer's choice at that moment, made on paper before anyone has looked at the car, fixes everything that can happen to the vehicle afterwards.
Those five map onto different outcomes at § 13-507(b). Notation 1 becomes a title carrying "a conspicuous notation that the vehicle is 'rebuilt salvage'" after inspection. Notation 2 can never be titled at all — "[t]he Administration may not issue a certificate of title for a vehicle if the salvage certificate for the vehicle bears a notation under § 13-506(c)(2)(ii)2". Notation 4 produces a "Flood Damaged" title. Notation 5 produces "X–Salvage". Note what is missing: there is no route by which a Maryland salvage history produces an unbranded title. The brand is not a penalty applied to bad repairs, it is the permanent consequence of the document the car was carrying when it entered the system.
"X–Salvage" is the brand outsiders read wrong, and it is worth spending a paragraph on because it appears on cars a buyer would otherwise be pleased with. It attaches to notation 5, which is a car an insurer acquired in a settlement where "the cost to repair the vehicle is 75% or less of the fair market value". An X–Salvage car is therefore not a heavily wrecked car and is not the same animal as rebuilt salvage — it is a car the insurer found uneconomic or inconvenient to fix, which in practice often means an older vehicle with moderate damage, or one where the § 13-506(c)(5) "economic or safety related decision" was simply to stop. Do not treat the two brands as interchangeable and do not read "X–Salvage" as a more serious version of salvage.
The same brand, however, covers a second and much less reassuring history. Section 13-507(b)(4) applies "X–Salvage" to a title issued against a salvage certificate bearing notation 5 "or" one "issued under § 13-506(d) of this subtitle" — and § 13-506(d) is the automotive dismantler and recycler's route. Under § 15-501(b)(1) that is a business of "[d]ismantling, destroying, or scrapping any vehicle for the purpose of reselling any of its usable parts". So a car that passed through a dismantler's yard and a car an insurer declined to repair at 60% damage arrive on the road wearing the identical word. The brand tells you the corridor, not the condition, and only the underlying VIN history separates the two.
The parts-only category deserves the same care in the other direction. It is Maryland's true dead end, but it has no memorable name. The insurer certifies the sentence, MVA notes it, and § 13-507(b)(2)(ii) permanently closes the title route; where the car was owner-retained, § 13-506.1(c)(2)(ii) also has MVA issue the salvage certificate and demand the plates back immediately. There is no rebuild, no inspection and no appeal written into the section. If a seller offers you a car described as "parts only title" and then explains how it can be brought back, the statute disagrees with them.
The naming is genuinely inconsistent across Maryland's own documents, which is a hazard when you are matching paperwork to a history report. Section C box 5 of form VR-028 says a recovered stolen car with damage at 75% or less "will be issued a Salvage Certificate branded 'Recovered Stolen.'" The instructions on the reverse of the same form describe the same category as "a Salvage Certificate branded 'Recovered Salvage'". Section 13-507(b)(4) calls the resulting title notation "X–Salvage". Three names for one path, two of them on a single sheet of paper. The form also quietly rewrites the statutory definition, rendering § 11-152(a)(1)'s "cost to repair the vehicle for legal operation on a highway" as the cost to repair it "for legal operation safely on a highway" — an added word that has no counterpart in the code.
The stolen-vehicle path is the one place where a salvage history can end on a title with no salvage certificate behind it. Under § 13-507(c) an insurer settling a theft claim applies for a salvage certificate, MVA makes the notation but "[m]ay not issue the salvage certificate until the vehicle is recovered". When it is recovered, MVA either issues the salvage certificate, or — if the insurer states the car "has sustained damage, except for flood damage, that costs 75% or less than the fair market value of the vehicle to repair" — issues "a certificate of title in the name of the insurance company in lieu of a salvage certificate". That car is also exempt from excise tax under § 13-810(a)(9), which covers "[a] vehicle acquired by an insurance company as a result of a comprehensive or collision claim". Read § 13-507(c)(4) before assuming the resulting title is clean: it states that subsection (b) applies to a title issued under subsection (c), which is the subsection that carries the notations. VR-028 routes the same case through box 7 and charges "a $200.00 fee" alongside the title application. Treat the precise brand outcome here as a reading of two subsections rather than a settled fact, and check the VIN record rather than the document.
Two last points a buyer should carry. Section 13-507(d) closes the out-of-state route: a title arriving with a foreign notation for a condition "substantially similar to a vehicle that is rebuilt salvage under Maryland law" must be issued here with "a similar notation" — a mapping onto Maryland's own vocabulary rather than a verbatim carry-over of the other state's word, so the phrase on the Maryland title may not match the phrase on the document it replaced. And MVA's consumer page compresses this entire scheme into two words, telling readers a vehicle may be "Salvage" or "Rebuilt" and that "[a] salvage vehicle cannot be registered or driven until it has been rebuilt, inspected, and approved." That is a fair summary of the process and a poor guide to the paperwork: "rebuilt" on its own is not a Maryland brand, the statutory phrase is "rebuilt salvage", and neither word will tell you whether you are looking at a 90% wreck, a flood car, a dismantler's shell or an insurer's economic write-off.
Sort the brands into two piles as you read them. One pile — salvage, rebuilt, reconstructed, prior salvage — describes a car that can legally return to the road once it passes inspection. The other — junk, scrap, non-repairable, certificate of destruction — is a permanent bar. A vehicle in the second pile can never be titled for road use again, whatever a seller tells you about how straight it is now.
Maryland carries a brand applied by another state forward onto its own title, so a washed document from a neighbouring state does not survive a transfer into MD.
Has This Maryland Car Ever Been Written Off?
A re-issued title can look clean over a total loss recorded in another state. Run the VIN and see every brand on the record, free, in seconds.
Salvage to Rebuilt: The Maryland Inspection
A salvage title is not a licence to drive. It is closer to a receipt for a wreck: the car is legally off the road until somebody repairs it, submits it for inspection, and gets a new certificate issued in the rebuilt category. Buying a salvage-titled car and driving it home is not a grey area — it is an unregistered, uninsurable vehicle on a public road, and Maryland will not put plates on it until the rebuilt certificate exists.
In Maryland the inspection is carried out by the Maryland Department of State Police Automotive Safety Enforcement Division. Read § 13-507(a)(2) carefully, because Maryland requires two different inspections and most summaries collapse them into one. The application for a title must be accompanied by both "[a] certificate of inspection issued by a county police department or the Department of State Police" and, separately, "[a] certificate of inspection as required under Title 23 of this article" — the ordinary Maryland safety inspection, which under § 23-106(b)(2) is obtained "from an inspection station" rather than from the police. Two certificates, two different bodies, two different questions.
The police inspection is the anti-theft one, and it is the only one this section of the process is about. MSP says the inspector "will check your vehicle's identification numbers (VIN) and verify that no stolen parts were used", and that on passing the inspector "will emboss and sign your salvage certificate". Nothing in that description touches brakes, tyres, structure or alignment. It is a check that the car in front of the inspector is the car on the certificate and that its components were not stolen from someone else's.
The statute names two possible issuers. Section 13-507(a)(2)(ii) accepts a certificate "issued by a county police department or the Department of State Police", so a county force can in principle perform it, but the programme in practice is run by the State Police Automotive Safety Enforcement Division, and that is who publishes the sites, the fee and the scheduling system. Section 13-507(a)(3) lets the Administration set the fee, has it "collected by the Administration or the Automotive Safety Enforcement Division", and then earmarks it: the money is paid to the Division "for the purpose of recovering the cost of administering the salvage inspection program and may not be credited to the Gasoline and Motor Vehicle Revenue Account". The inspection funds itself and does not subsidise roads.
There is a sequencing problem worth knowing about before you plan around it. Section 13-507(a)(2) requires both certificates to accompany the title application. MSP's published workflow says that after passing the salvage inspection "[y]ou can then apply to the MVA for a title and a 30 day temporary registration to get a regular safety inspection" — that is, the safety certificate is obtained after the title application, using a temporary registration issued on the strength of it. The two cannot both be literally true of the same document at the same moment. Treat this as a procedural drift between the statute and the agency's own instructions rather than a settled reading, budget for two visits and a temporary tag, and ask the branch office which order they want the paper in.
The roadworthiness requirement is a second thing that reads differently than it looks. MSP tells applicants "[y]our vehicle must be roadworthy" and "must be fully repaired" before it is presented — but the inspection MSP then performs tests neither of those things. Roadworthiness is a precondition MSP imposes and does not verify; the verification happens later, at a licensed inspection station under Title 23. A passed salvage inspection is evidence about identity and parts provenance. It is not, and does not claim to be, evidence that the repair was done well.
Scheduling is entirely online and paid up front. You create an account on the Salvage Inspection site with your name, address, contact details, driver's licence number and email; choose a location, date and time; enter the vehicle's year, make, model, VIN and salvage certificate information; pay the $75 fee by credit card; and print or save the confirmation email to bring with you. The fee is charged at booking rather than at the gate, which means a missed or refused appointment is a real loss rather than a rescheduling.
What to bring is a longer list than most states ask for: valid ID; the salvage certificate, which MSP identifies as "MVA Form VR-108 or similar"; the vehicle itself; the appointment confirmation email; proof of ownership such as a bill of sale or dealer reassignment; and repair receipts. If you are representing a dealer, bring proof you are an authorised dealer; if you are not the owner, bring a signed authorisation letter from the owner. The repair receipts are not a formality — they are how the inspector traces the provenance of the parts that were fitted, which is the entire subject of the inspection.
One refusal a buyer would not guess concerns the VIN plate itself. If the VIN plate is missing or damaged, the ordinary salvage inspection cannot deal with the car at all: MSP directs that it "must be inspected by the Auto Theft Unit at the Glen Burnie site on Tuesdays from 8:30 a.m. to 12:30 p.m." That is a single four-hour window, once a week, at a location that does not appear on MSP's own published list of salvage inspection sites. If you are buying a rebuilt car with a damaged VIN plate, understand that you are buying a queue as well as a car.
The published sites are seven, and their geography is the practical constraint. Beltsville, 11609 Edmonston Road; the Finzel Weigh Station site, eastbound I-68 at mile marker 31 in Garrett County; Frederick, 1601 Bowmans Farm Road; Hagerstown, 18306 Colonel Henry K Douglas Drive; La Plata, 9500 Mitchell Road; Perryville, at the MdTA Inspection Garage, 1 Turnpike Drive; and Salisbury, 254 Tilghman Road. Two of those are highway enforcement facilities rather than garages, none is in Baltimore City, and the Eastern Shore and far west are each served by a single site. Confirm the location is still operating when you book rather than when you set off.
A second refusal is environmental and is enforced on the spot. MSP warns that "[a]ny vehicle, including tow vehicles, found to be leaking environmentally unsafe liquids on salvage location parking lots or garage floors must be completely removed", and that "[i]f your salvage vehicle is leaking, the salvage inspection will not be conducted and you may also be subject to a fine." A car that has sat on a lot for months waiting on parts is exactly the car most likely to fail this before anyone opens the bonnet.
Two routes skip the salvage inspection entirely, and both are easy to miss. The first is the owner-retention route: MSP states that "[i]f you have received an MVA form VR-310 stating your vehicle needs to pass a safety inspection within 90 days, you do not need a salvage inspection." That is the § 13-506.1(c)(2)(i) notice, and it means a Maryland owner-retained total loss is branded and safety-inspected but never given the anti-theft and parts-provenance check that a purchased salvage car must pass. The second is reciprocity: MSP says that if the vehicle "has already had a salvage inspection in another state, you may not need to have the vehicle inspected again in Maryland." That is stated as a possibility rather than a rule, so confirm it in writing with MSP before relying on it — MSP directs anyone unsure whether an inspection is required to email the Division first.
Passing gets you an embossed and signed salvage certificate, not a title. From there you apply to MVA — the agency recommends doing it in person at a full-service branch for salvage and rebuilt vehicles, because staff can check the file for completeness — with a Certificate of Title application (VR-005), proof of ownership, bills of sale or receipts for major repairs and parts, valid identification, and payment of the title fee, the salvage inspection fee, motor vehicle excise tax and any registration fees. Note that MVA's salvaged-vehicles page also lists form VR-028 among the documents to submit, although that form describes itself as an application for a salvage certificate or owner retention rather than a rebuilt-title application; ask the branch which forms your particular route actually needs before you fill anything in.
Maryland Department of State Police Automotive Safety Enforcement Division
Inspection fee: $75, paid by credit card when the inspection is scheduled
Official MD rebuilt-title inspection pageUnderstand what these inspections are usually for, because buyers routinely misread them. The primary purpose in most states is anti-theft verification — confirming the VIN plates are original and untampered, and that the parts bolted onto the car were bought rather than stolen, which is why receipts for major components are demanded. A rebuilt inspection is not a structural engineering assessment, and passing it is not a statement that the repair was done well.
So the certificate on the wall tells you the car is legal. It does not tell you the frame was pulled straight, the airbag module was replaced rather than reset, or the welds are where a factory would have put them. That is what your own independent pre-purchase inspection is for, and on a rebuilt car it is not optional.
What to ask for before you agree a price
- 1Photographs of the car before repair. A rebuilder who did honest work kept them; one who did not will find a reason they are unavailable.
- 2The parts invoices, especially for airbags, structural components and safety restraints. Salvaged airbags are a known and dangerous shortcut.
- 3The Maryland inspection paperwork in the seller's name, matching this VIN, not a photocopy of somebody else's.
- 4The insurance total-loss settlement, if the seller has it — it names the damage the carrier actually paid out on.
- 5An independent inspection from a shop that does collision work, on a lift, before money changes hands. Budget for it as part of the purchase.
Then put the sale itself on paper. Write the brand into your Maryland bill of sale in the seller's own words — a rebuilder who will not describe the car in writing as what its title says it is has told you something. And before the money moves, check whether anyone still holds a security interest in it. Rebuilt cars are bought at auction and repaired on credit far more often than clean ones are, and a lender's claim survives the repair, the inspection and the new certificate.
What a Rebuilt Title Actually Costs You
The sticker discount is real. What people underestimate is that the brand keeps charging you — every year you own the car, and again on the day you sell it.
Insurance is narrower and sometimes unavailable
Liability cover is normally fine. Physical damage is where the problem lives: several large insurers decline comprehensive and collision on a rebuilt vehicle outright, and those that write it settle any future claim against the reduced branded value. Get a quote against the actual VIN before you agree a price.
Most lenders will not finance it
Branded collateral is hard to value and hard to move on repossession, so banks and captive finance arms generally decline. Some credit unions lend at a shorter term and a higher rate. In practice it is a cash purchase — which also removes the lender's appraisal, one of the few independent checks in a normal transaction.
The resale discount does not fade
A branded car trades well below a comparable clean one, commonly quoted around 20% to 40% depending on the vehicle and the documentation. The gap does not close with age, because every future buyer runs the same VIN you are running now. Most dealers will not take one in part-exchange at all.
Repair quality is the real variable
A car repaired with new OEM panels on a jig can be entirely sound. One straightened by eye with junkyard parts and a reset airbag light shows up later as pulling under braking, doors that stop sealing, or restraints that do not fire. Nothing on the title separates the two — only the documentation and a lift.
Should You Ever Buy a Salvage or Rebuilt Car?
Sometimes, yes. The honest answer is that it depends on what the car was hit by and what you need the car to do — and it is a judgement most buyers can make for themselves once they know what to separate. Two lists, and they are not close calls.
Cases where the discount is genuinely worth it
- Hail damage on an otherwise untouched car. It is cosmetic, it totals cars on paint cost alone, and the mechanical vehicle underneath is exactly what it was.
- A recovered theft with no collision damage, where the write-off happened because the insurer had already paid the claim before the car turned up.
- An older, low-value car totalled by modest damage. On a $4,000 car it takes very little to cross a threshold, and the repair may be one panel.
- A car you intend to keep for a decade and run into the ground. The resale penalty only bites if you plan to sell.
- A repair you can fully document — pre-repair photographs, parts invoices, and a shop you can phone.
Cases where the discount is a warning, not a bargain
- Any flood history. Water gets into loom connectors, control modules and seat-belt pretensioners, and the failures arrive months later in an order nobody can predict.
- Deployed airbags with no invoice for the replacement modules. A reset light over a spent or salvaged restraint system is the most dangerous shortcut in the trade.
- Structural or unibody repair without documented frame measurements. If the shell is out of alignment the car will never track, brake or crash correctly.
- A rebuilder who cannot produce pre-repair photographs, or who bought and re-titled the car in the last few weeks.
- Anything you need to finance, insure comprehensively, or resell within a couple of years — the brand blocks all three.
The flood exception is not a preference. Every other category on these lists is a matter of price and documentation. Flood is the one where a well-presented car and a ruined car look identical for the first year, and where the damage is distributed through the electrical system rather than concentrated somewhere a mechanic can look. Flood cars also travel: they are bought cheaply after a storm, cleaned, and sold hundreds of miles away, which is why the state on the current title tells you very little about where the water was.
What a Salvage Check Does Not Tell You
A title brand is a fact about the car's damage history as reported by an insurer. It is silent on who owns the car, what the odometer has done, and whether anyone is looking for it. Those live in different systems and are different searches — a car with a spotless brand record can still be encumbered, clocked, or stolen.
More Maryland Vehicle Guides
Everything else worth checking before you put a Maryland car in your name.
Salvage Title Check in Other States
Worth comparing if the car you are looking at was titled somewhere else before it reached Maryland— the threshold that branded it, or failed to, was that state's rather than this one's.
View the full salvage title check hubMaryland Salvage Title Check — Frequently Asked Questions
How do I check for a salvage title in Maryland?+
Enter the 17-character VIN in the search box on this page. Title brands are recorded against the VIN, not against the paper title the seller is holding, so a VIN search reaches a brand the document does not show. We cross-reference NMVTIS — which aggregates title-brand records from the Maryland Motor Vehicle Administration and every other state titling agency — along with insurance total-loss feeds and salvage-auction records.
What counts as a total loss in Maryland?+
Maryland uses a percentage threshold: the salvage line sits at 75% of what the vehicle was worth before the damage. Who that test binds varies by state — sometimes the insurer's own total-loss declaration brands the car and the percentage never applies, and sometimes the percentage governs only damage no insurer is covering. The rule is set by Md. Code, Transp. §§ 11-152 ("Salvage" defined); 13-117 (corrected certificate of title); 13-506 (salvage certificates); 13-506.1 (owner retention); 13-507 (title after salvage); 13-810(a)(9) (excise tax exemption); 15-501 (automotive dismantler and recycler defined); 23-106 (inspection certificate on transfer); 25-201 (abandoned vehicle defined). Whichever test applies, what triggers the brand is the insurer's decision, not the severity of the damage as a mechanic would judge it — which is why a lightly damaged older car and a badly damaged newer one can end up carrying the same title.
What title brands does Maryland use?+
Maryland records these brands through the Maryland Motor Vehicle Administration: Salvage, rebuilt salvage, Flood, Non-Repairable. The wording matters more than it looks — the word for a repaired total loss differs between states, and a seller describing the car in a neighbouring state's vocabulary is either careless or moving cars across a state line.
How does a salvage car get a rebuilt title in Maryland?+
It has to be repaired and then cleared by the Maryland Department of State Police Automotive Safety Enforcement Division before it can be re-titled and driven; the section on the Maryland inspection above covers what that involves, and whether a physical inspection is guaranteed or only happens on the cars the state picks. The inspection fee is $75, paid by credit card when the inspection is scheduled. Passing it is not a statement that the repair was done well — in most states the inspection is an ownership and anti-theft check, which is why it wants receipts for major parts rather than frame measurements.
Does a salvage brand disappear if the car is re-titled in another state?+
No. The brand is attached to the VIN in NMVTIS, and NMVTIS is fed by every state titling agency, by insurers, and by salvage yards. A paper title issued in a second state can come out looking clean — that is what title washing is — but the VIN record does not reset when the car crosses a state line. Maryland also carries a brand applied elsewhere forward onto its own title.
Can you insure and finance a rebuilt-title car in Maryland?+
Liability cover is usually available. Comprehensive and collision often are not, and most banks will not lend against branded collateral, so rebuilt cars tend to be cash purchases. Get a written quote from your own insurer against the VIN before you agree a price, not after.
Is it safe to buy a rebuilt car in Maryland?+
It depends on what the damage was and who repaired it. Hail, a recovered theft or a rear-end hit on an older car can total a vehicle on economics alone and leave nothing structurally wrong. A flood car, deployed airbags with no documented replacement, or a repaired unibody is a different proposition. Ask for the pre-repair photographs, the parts invoices and the Maryland inspection paperwork, then pay an independent shop to put it on a lift. If the seller cannot produce the repair record, you are buying the repair blind.
Does a clean salvage check mean the car was never damaged?+
No, and this is the limit worth understanding. A brand only exists if an insurer wrote the car off and reported it. Damage repaired privately, out of pocket, or by a driver who never made a claim leaves no brand at all — and on an older car, where repair costs easily exceed a low book value, owners often avoid claiming for exactly that reason. A clean brand record is good news about the paperwork, not a report on the bodywork.
Maryland sources
The Maryland-specific statements above come from these official pages. Thresholds, fees and brand wording do get amended — check the source before relying on a figure in a transaction.
Vérifications VIN connexes
Plus d'outils pour vérifier l'historique de tout véhicule
Run Your Free Maryland Salvage Title Check
One VIN, every brand ever recorded against it, in any state. Two minutes now against a write-off that would otherwise follow the car into your name.
Or get the full VIN history report