Cheapest Cars To Insure in 2025: An Investigative Look at What Actually Lowers Your Premium
Which vehicles actually cost the least to insure in 2025? We dug into insurer loss data, IIHS crash ratings, and NHTSA theft stats to separate marketing fluff from real savings.
On this page
- How Insurers Actually Set Rates by Vehicle
- The Cheapest Cars To Insure: Model-by-Model Breakdown
- Cheapest Classic Cars To Insure: A Separate Calculation
- Cost vs. Risk: Choosing Minimum Liability vs. Full Coverage
- Body Style and Segment: What the Data Shows
- Theft Rates and Comprehensive Premiums
- State-Level Variations That Shift the Rankings
- Discounts That Stack: Reducing Premiums Beyond Vehicle Choice
- The Auction and BHPH Angle
- Putting It All Together: A Decision Framework
For anyone shopping the used-car market—whether at a franchise dealer, a buy-here-pay-here lot, or through a private-party Craigslist listing—the sticker price is only half the equation. Insurance premiums can quietly add $1,000 to $3,000 or more per year to the true cost of ownership, a range confirmed by the National Association of Insurance Commissioners (NAIC), which reported an average annual auto-insurance expenditure of $1,771 in its most recent State of Auto Insurance report. Identifying the cheapest cars to insure before you sign a bill of sale is one of the most effective ways to keep total costs under control, yet surprisingly few buyers bother to get insurance quotes while they are still comparison-shopping vehicles. What follows is a data-driven examination of which models, body styles, and vehicle categories consistently produce the lowest premiums—and why.
The short answer
Midsize sedans and small SUVs from mainstream brands—think Honda CR-V, Subaru Outback, Jeep Cherokee, and the Subaru Forester—consistently land at or near the bottom of insurer rate sheets because they combine moderate repair costs, strong IIHS crash-test ratings, and below-average theft frequency. Expect annual full-coverage premiums roughly 15–25% below the national average for these models.
How Insurers Actually Set Rates by Vehicle
Before examining specific models, it is worth understanding the machinery behind the premium you are quoted. Insurers rely on a complex blend of driver-level variables (age, credit-based insurance score where permitted, driving record) and vehicle-level variables. The vehicle-level factors include the Insurance Institute for Highway Safety (IIHS) crashworthiness rating, the Highway Loss Data Institute (HLDI) collision and comprehensive loss data, the National Insurance Crime Bureau (NICB) Hot Wheels theft report, and manufacturer-quoted parts pricing. A car that is cheap to buy can still be expensive to insure if its theft rate is high or its body panels require specialized labor—a lesson many first-time buyers of entry-level luxury cars learn the hard way.
The HLDI loss-data pipeline
The HLDI, an affiliate of the IIHS funded by auto insurers, publishes loss results for virtually every make, model, and trim sold in the United States. Vehicles are scored relative to an index of 100, which represents the average for all passenger vehicles. A collision-loss index of 80 means the vehicle's collision claims cost insurers 20% less than average; an index of 130 means 30% more. When you see a model described as 'cheap to insure,' the underlying reason is almost always a low HLDI loss index across collision, comprehensive, and personal-injury categories.
The Cheapest Cars To Insure: Model-by-Model Breakdown
Drawing on HLDI loss data, Insure.com's annual rate survey, and Bankrate's 2024–2025 model-year premium analysis, several vehicles repeatedly surface at the bottom of premium rankings. Bankrate reported in its 2024 analysis that the Subaru Outback carried an average annual full-coverage premium of approximately $1,343, while the Honda CR-V came in at roughly $1,398—both well below the national average. The Jeep Cherokee, the Subaru Forester, and the Honda HR-V also clustered in a similar sub-$1,500 band. These are not coincidences; they share structural characteristics that make them actuarially favorable.
Common traits of low-premium vehicles
- Mainstream brand with wide parts availability and competitive labor rates at independent shops—reducing insurer repair payouts.
- IIHS Top Safety Pick or Top Safety Pick+ rating, which correlates with lower personal-injury claim severity.
- Below-average theft frequency as reported by the NICB, which lowers comprehensive premiums.
- Moderate horsepower (typically under 200 hp), which reduces collision frequency among younger demographics.
Models to watch for used-car buyers
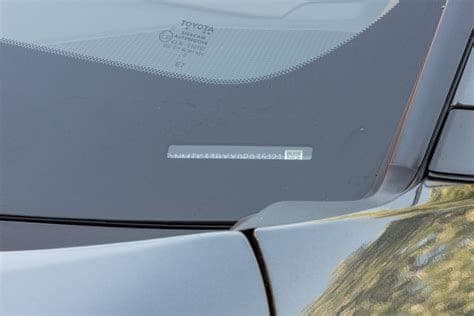
Used-car shoppers benefit from an additional dynamic: depreciation has already occurred, so the insured value is lower, which mechanically reduces collision and comprehensive premiums. A 2018–2020 Honda CR-V or Subaru Forester purchased for $18,000–$22,000 on the secondary market will carry a lower premium than the same model bought new at $32,000+, all else being equal. Before signing, request the vehicle's VIN and run a vehicle history report to confirm the title is clean—a salvage or rebuilt title brand, recorded through NMVTIS, can paradoxically increase comprehensive and collision premiums at some carriers even though the car's market value is lower, because insurers view prior damage as a predictor of future claim complications.
Cheapest Classic Cars To Insure: A Separate Calculation
Buyers interested in older vehicles should know that the cheapest classic cars to insure operate under an entirely different underwriting model. Specialty insurers like Hagerty, Grundy, and American Collectors Insurance offer agreed-value policies rather than actual-cash-value policies, meaning you and the insurer negotiate the car's worth up front. Because classic cars are typically driven fewer than 2,500 miles per year—a mileage cap most specialty policies enforce—the exposure to collision loss is dramatically lower. Hagerty has publicly stated that its average annual premium for a classic car is in the range of $300 to $700, a fraction of what a daily-driver policy costs, because claim frequency is so low.
Which classics cost the least?
Among the cheapest classic cars to insure are domestic models with abundant, inexpensive parts: the Ford Mustang (1965–1973), the Chevrolet C10 pickup, and the Volkswagen Beetle. Their reproduction-parts ecosystems are so mature that repair costs stay low even after a fender bender. A 1966 Mustang coupe insured at an agreed value of $25,000 might carry an annual premium of $350–$500 through Hagerty, while a comparable-value European classic with scarce parts could cost double. The key requirement is that the vehicle must not be used as a daily driver; if it is, standard auto insurance applies, and the savings evaporate.
Cost vs. Risk: Choosing Minimum Liability vs. Full Coverage
One of the most consequential decisions a used-car buyer faces is whether to carry only the state-minimum liability coverage or to add collision and comprehensive. This choice interacts directly with the vehicle's value and your financial exposure. According to the Insurance Information Institute (III), the average annual cost of liability-only coverage in the U.S. was approximately $622 in 2022, while full coverage averaged roughly $1,771—a gap of nearly $1,150 per year. On a vehicle worth $8,000 or less, some financial advisors argue that dropping collision coverage and self-insuring the loss makes mathematical sense, particularly if the annual collision premium exceeds 10% of the car's value.
Running the numbers on a $6,000 used sedan
Consider a 2015 Toyota Corolla purchased for $6,000. Full coverage with a $500 deductible might run $1,400 per year; liability only might cost $550. The collision-and-comprehensive portion—$850—represents over 14% of the car's value annually. If you kept that $850 in a savings account for two years, you would have $1,700, enough to replace the car outright if it were totaled. On the other hand, a $25,000 Subaru Outback purchased with a credit-union loan will almost certainly require full coverage as a condition of the lien, and the collision premium of perhaps $500–$700 per year is a much smaller percentage of the asset being protected. The trade-off is not abstract; it is arithmetic.
Title brands change the insurance equation
A vehicle with a salvage or rebuilt title recorded in NMVTIS can be refused coverage by some major insurers, and those that do write the policy may exclude collision or limit payouts to a reduced value. Always run a VIN check before purchasing any used car, and contact your insurer with the VIN before closing the deal to confirm the vehicle is insurable at the rate you expect.
Body Style and Segment: What the Data Shows
Across HLDI data and commercial rate surveys, a clear hierarchy emerges by vehicle segment. Midsize sedans and small crossover SUVs consistently produce the lowest premiums. Sports cars, high-performance trucks, and luxury vehicles of any size land at the top. The III has noted that two-door coupes tend to carry premiums 10–15% higher than four-door sedans of comparable value, partly because actuarial data associates two-door vehicles with higher-risk driving behavior in aggregate.
- Midsize sedans (Camry, Accord, Malibu): typically 10–20% below the all-vehicle average premium per Bankrate's annual survey.
- Small SUVs/crossovers (CR-V, RAV4, Forester): similar to midsize sedans, sometimes slightly lower due to superior crash-test geometry.
- Minivans (Odyssey, Sienna, Pacifica): among the cheapest to insure per HLDI, because their drivers tend to be low-risk parents.
- Full-size trucks (F-150, Silverado): moderate premiums, but high repair costs push collision indexes above average.
- Sports cars and performance trims (Camaro SS, Mustang GT, WRX STI): premiums 30–60% above average per HLDI collision-loss indexes.
Theft Rates and Comprehensive Premiums
Comprehensive coverage—the portion that pays for theft, vandalism, and weather damage—is heavily influenced by how often a particular model is stolen. The NICB's 2023 Hot Wheels report found that the Hyundai Elantra and Hyundai Sonata experienced a dramatic spike in thefts (a 1,049% increase between 2020 and 2023 for certain model years, per NICB data), largely due to the now-infamous 'Kia Boys' USB-ignition exploit affecting 2011–2021 Hyundai and Kia models without immobilizers. Despite their low purchase prices, those affected model years now carry inflated comprehensive premiums—and some insurers, including Progressive and State Farm in certain states, temporarily declined to write new policies on them at all. The lesson: a low MSRP does not guarantee a low insurance cost if the car's theft profile is unfavorable.
How to check before you buy
Before committing to a purchase, take the VIN to your insurer's online quoting tool or call your agent. Most carriers will generate a bindable quote with just the VIN, your ZIP code, and your driver's license number. This 10-minute step can reveal a $500-per-year surprise before it becomes your problem. Cross-reference the model year against the NICB Hot Wheels list and the HLDI's publicly available loss-data tables to understand the structural reasons behind whatever premium you are quoted.
State-Level Variations That Shift the Rankings
Insurance is regulated at the state level, and premiums for the same vehicle can vary enormously depending on where you register it. Michigan, which until recent reforms under Public Act 21 of 2019 required unlimited personal-injury protection (PIP), has historically carried the highest average premiums in the nation—the III reported Michigan's average expenditure at $2,941 in 2022. Maine, on the other hand, averaged approximately $999. A Honda CR-V that costs $1,350 per year to insure in Ohio could cost $2,200 or more in Detroit. Buyers relocating or purchasing across state lines should re-quote insurance in their registration state before finalizing the deal.
Discounts That Stack: Reducing Premiums Beyond Vehicle Choice
Choosing a low-premium vehicle is the foundation, but several additional levers can further reduce costs. These are particularly relevant for used-car buyers who may be stretching their budgets.
- Raise your deductible: Moving from a $500 to a $1,000 deductible typically reduces collision premiums by 15–20%, according to the III.
- Bundle with renters or homeowners insurance: Most carriers offer a multi-policy discount of 5–15%.
- Ask about low-mileage discounts: If you drive fewer than 7,500 miles per year, carriers like GEICO and USAA offer reduced rates.
- Install an anti-theft device: Particularly relevant for older Hyundai and Kia models; an aftermarket immobilizer can restore insurability and lower comprehensive costs.
- Shop at least three carriers: The III recommends comparing quotes from at least three insurers, because rate algorithms differ and the cheapest carrier for one vehicle may not be cheapest for another.
- Maintain a clean driving record: A single at-fault accident raises premiums by an average of 49%, per Bankrate's 2024 analysis.
The Auction and BHPH Angle
Buyers purchasing vehicles at Copart or IAA auctions—whether for personal use or resale—face a unique insurance challenge. Many auction vehicles carry salvage titles, and as noted, salvage-titled cars can be difficult or impossible to insure for full coverage through standard carriers. Specialty insurers such as Foremost (a Farmers subsidiary) and some regional mutuals will write policies on rebuilt-title vehicles, but premiums are often 20–40% higher than for clean-title equivalents, and payouts may be capped at 80% of comparable clean-title market value. BHPH (buy-here-pay-here) lots often require buyers to carry full coverage as a condition of the in-house financing, and some BHPH dealers bundle insurance through affiliated agencies at rates that are not competitive. Independent comparison shopping is essential in this segment.
Putting It All Together: A Decision Framework
The evidence points to a clear buying strategy for cost-conscious consumers. First, target a mainstream midsize sedan, small SUV, or minivan from a brand with wide parts availability—Honda, Toyota, Subaru, and Jeep (for the Cherokee specifically) dominate the low-premium rankings. Second, verify the vehicle's title status through a vehicle history report and confirm insurability with your chosen carrier before closing. Third, match your coverage level to the vehicle's value: full coverage for anything above roughly $10,000 in value, and a hard look at liability-only for vehicles under $6,000–$8,000. Fourth, layer on every applicable discount. Fifth, re-quote annually, because insurers reshuffle their rate filings with state regulators regularly, and your cheapest carrier this year may not be cheapest next year.
What to do next
Pick two or three models from the low-premium list above, find specific VINs for sale in your area, and enter each VIN into your insurer's online quote tool right now—before you visit a single dealership. The 15 minutes you spend will reveal the true annual cost of each vehicle and may redirect your search entirely.
CarCheckerVIN Editorial Team
In-house automotive research team
The CarCheckerVIN editorial team combines decades of automotive industry, dealer, and journalism experience to produce trustworthy buying, selling, and ownership guidance backed by NMVTIS, NICB, and manufacturer data.
Frequently asked questions
- What is the absolute cheapest car to insure?
- Based on Bankrate's 2024–2025 rate analysis, the Subaru Outback consistently ranks as one of the single cheapest vehicles to insure in the United States, with average annual full-coverage premiums around $1,343. The Honda CR-V and Jeep Cherokee follow closely. These models benefit from low HLDI collision-loss indexes, strong IIHS safety ratings, and below-average theft rates reported by the NICB—all factors that directly reduce what insurers charge.
- What is the $3000 rule for buying cars?
- The so-called $3,000 rule is a personal-finance heuristic, not a statute. It suggests that if your annual insurance premium (particularly collision and comprehensive) exceeds roughly 10% of your car's market value—common when a car is worth $3,000 or less—you should drop to liability-only coverage and self-insure the loss. The logic is that paying $500+ per year to protect a $3,000 asset is mathematically inefficient compared to saving that premium in an emergency fund.
- Is $200 a month high for car insurance?
- At $2,400 per year, $200 per month is above the national average. The NAIC's most recent data pegged the average U.S. auto-insurance expenditure at approximately $1,771 annually, or about $148 per month. However, $200 per month may be normal for drivers under 25, those with at-fault accidents on their record, residents of high-premium states like Michigan or Louisiana, or owners of vehicles with elevated theft or repair costs. Shopping at least three carriers is the fastest way to verify whether your rate is competitive.
- What cars are in insurance group 1, 2, 3, 4?
- Insurance groups 1 through 4 are a classification system used in the United Kingdom by the Association of British Insurers—they do not apply in the United States. American insurers do not assign vehicles to numbered groups. Instead, U.S. carriers use HLDI loss-data indexes, IIHS crash ratings, NICB theft statistics, and proprietary algorithms to price each vehicle individually. The closest U.S. equivalent is checking a specific model's HLDI collision and comprehensive loss index, where a score below 100 indicates lower-than-average insurer costs.
Ready to check a VIN?
Run a free VIN check
Decode any vehicle in under 60 seconds.